Author: Ankur Jhavery

  • ELSS Funds: How to Save Tax While Building Wealth

    ELSS Funds: How to Save Tax While Building Wealth

    Tax Saving ELSS Funds

    Tax season in India often brings stress. But what if you could save tax and grow your wealth at the same time? That is exactly what ELSS (Equity Linked Savings Scheme) funds offer.

    What Is ELSS?

    ELSS is a type of mutual fund that invests primarily in equities (stocks). What makes it special is the tax benefit — investments up to ₹1.5 lakh per year qualify for a deduction under Section 80C of the Income Tax Act.

    This means if you are in the 30% tax bracket, investing ₹1.5 lakh in ELSS can save you up to ₹46,800 in taxes (including cess).

    ELSS vs Other Tax-Saving Options

    Section 80C offers many investment options. Here is how ELSS compares:

    Option Lock-in Period Expected Returns
    ELSS 3 years 10-15% p.a.
    PPF 15 years 7-8% p.a.
    NSC 5 years 7-8% p.a.
    Tax-Saving FD 5 years 6-7% p.a.

    ELSS has the shortest lock-in period (just 3 years) and the highest return potential among all 80C options.

    How Does ELSS Work?

    1. You invest in an ELSS fund (via SIP or lump sum).
    2. Each investment unit has a 3-year lock-in from the date of purchase.
    3. The fund manager invests your money in a diversified portfolio of stocks.
    4. After 3 years, you can redeem your units or stay invested for higher returns.

    SIP in ELSS: The Smart Strategy

    Instead of investing ₹1.5 lakh at the end of the financial year in a rush, set up a monthly SIP of ₹12,500. Benefits:

    • Spreads your investment over the year
    • Averages out market volatility
    • No last-minute tax planning stress
    • Each month’s SIP has its own 3-year lock-in, so units start maturing month by month after 3 years

    Tax on ELSS Returns

    Long-term capital gains (LTCG) above ₹1.25 lakh per year from ELSS are taxed at 12.5%. Gains up to ₹1.25 lakh are completely tax-free. This is still much better than the tax treatment of FD interest, which is taxed at your slab rate.

    Who Should Invest in ELSS?

    • Salaried individuals looking to save tax under 80C
    • Self-employed professionals and business owners with tax liability
    • Anyone who wants market-linked returns with a short lock-in
    • First-time investors — ELSS is a great entry point to equity investing

    Start Saving Tax with Bachatt

    Bachatt helps you pick the right ELSS fund for your profile. Our AI-powered recommendations ensure you get the best tax-saving fund matched to your risk appetite. Start your ELSS SIP today — save tax, build wealth.
  • SIP vs Lump Sum: Which Is Better for You?

    SIP vs Lump Sum: Which Is Better for You?

    SIP vs Lump Sum Investment

    One of the most common questions new investors ask is: should I invest through a SIP or put in a lump sum? Both methods have their merits, and the right choice depends on your financial situation and goals.

    What Is a SIP?

    A Systematic Investment Plan (SIP) lets you invest a fixed amount regularly — typically monthly — into a mutual fund. Think of it like a recurring deposit, but instead of a fixed return, your money is invested in the market.

    For example, you could set up a SIP of ₹2,000 every month. On a fixed date, this amount is automatically deducted from your bank account and invested in your chosen fund.

    What Is Lump Sum Investment?

    A lump sum investment means you invest a large amount at one go. For instance, if you receive a bonus of ₹1 lakh, you invest the entire amount at once into a mutual fund.

    SIP: The Advantages

    • Rupee cost averaging: When markets are down, your SIP buys more units. When markets are up, it buys fewer. Over time, this averages out your cost per unit.
    • Discipline: SIPs build a regular saving habit. You invest automatically without thinking about market timing.
    • Affordable: Start with as little as ₹100 or ₹500 per month.
    • Reduces emotional decisions: You do not panic and sell during market dips because investing happens automatically.

    Lump Sum: The Advantages

    • Higher returns in rising markets: If you invest when the market is low and it rises, your entire investment benefits.
    • Simplicity: One transaction, and you are done.
    • Good for windfalls: If you receive a bonus, inheritance, or sale proceeds, lump sum makes sense.

    When Should You Choose SIP?

    SIP is ideal when:

    • You earn a regular salary or income
    • You are new to investing and want to start small
    • You want to build a long-term corpus for goals like retirement or children’s education
    • You do not want to worry about market timing
    • You have irregular income (like many self-employed individuals) and want flexibility

    When Should You Choose Lump Sum?

    Lump sum works well when:

    • You have a large amount ready to invest
    • Markets have corrected significantly (buying opportunity)
    • You have a long-term horizon and can handle short-term volatility

    The Verdict: Why Not Both?

    The best strategy for most people is to run a regular SIP and invest lump sums whenever you have extra money. This way, you get the discipline of SIP and the opportunity of lump sum investing.

    A Real Example

    Consider Ramesh, a small business owner. He sets up a monthly SIP of ₹5,000. During Diwali, his business does well and he has extra ₹50,000. He invests that as a lump sum. Over 10 years, his combined approach gives him the best of both worlds — consistent investing plus bonus growth.

    Start Your SIP with Bachatt

    Bachatt makes SIP investing incredibly simple. Set up your SIP in under 2 minutes, choose from curated funds suited to your goals, and watch your wealth grow. No jargon, no complexity — just smart saving.

  • What Are Mutual Funds? A Simple Guide for Every Indian

    What Are Mutual Funds? A Simple Guide for Every Indian

    Mutual Funds Guide

    If you have ever heard your friends, family, or colleagues talk about mutual funds but felt confused about what they actually are, you are not alone. Millions of Indians are in the same boat. The good news? Mutual funds are far simpler than they sound.

    What Is a Mutual Fund?

    Think of a mutual fund as a big pool of money collected from many people like you. This money is then managed by a professional fund manager who invests it in stocks, bonds, gold, or other financial instruments. You do not need to be an expert — the fund manager does the hard work for you.

    When you invest in a mutual fund, you buy “units” of that fund. As the investments grow, the value of your units increases. It is that simple.

    Why Are Mutual Funds Popular in India?

    India has seen a massive surge in mutual fund investments over the past decade. Here is why:

    • Low starting amount: You can start with as little as ₹100 through a SIP (Systematic Investment Plan).
    • Professional management: Expert fund managers handle your money, so you do not need deep market knowledge.
    • Diversification: Your money is spread across many investments, reducing risk.
    • Liquidity: You can withdraw your money when you need it (in most fund types).
    • Tax benefits: Certain mutual funds like ELSS help you save tax under Section 80C.

    Types of Mutual Funds You Should Know

    There are broadly three types based on what they invest in:

    1. Equity Mutual Funds

    These invest primarily in stocks. They have the potential for higher returns but come with higher risk. Best suited for long-term goals like retirement or children’s education.

    2. Debt Mutual Funds

    These invest in bonds and fixed-income instruments. They are less risky than equity funds and suitable for short to medium-term goals.

    3. Hybrid Mutual Funds

    These invest in a mix of equity and debt, offering a balance between risk and return.

    How to Start Investing in Mutual Funds

    Getting started is easier than ever, especially with apps like Bachatt:

    1. Complete your KYC: You need your PAN card, Aadhaar, and a bank account.
    2. Choose a fund: Based on your goal and risk appetite.
    3. Start a SIP or invest a lump sum: SIPs are great because they build discipline and average out market ups and downs.
    4. Stay invested: The longer you stay, the more your money can grow through compounding.

    Common Myths About Mutual Funds

    Myth 1: “Mutual funds are only for the rich.”
    Reality: You can start with just ₹100.

    Myth 2: “Mutual funds are very risky.”
    Reality: There are funds for every risk level — from ultra-safe liquid funds to aggressive equity funds.

    Myth 3: “I need to understand the stock market.”
    Reality: Fund managers do that for you.

    The Power of Starting Early

    Let us look at a simple example. If you invest ₹5,000 per month starting at age 25, with an average return of 12% per year, by the time you are 50, you could have over ₹95 lakhs. But if you start at 35, you would have only about ₹30 lakhs. That is the magic of compounding — the earlier you start, the more your money works for you.

    Start Your Mutual Fund Journey with Bachatt

    At Bachatt, we believe every Indian deserves access to wealth creation. Our platform makes mutual fund investing simple, accessible, and jargon-free. Whether you are a shopkeeper, a freelancer, or a first-time investor, Bachatt is designed for you.

    Download the Bachatt app today and take your first step towards financial freedom.

  • Chapter 1: Mutual Fund Investment Landscape

    Chapter 1: Mutual Fund Investment Landscape

    While we try to answer some of the below questions that the investors ask:

    “Which mutual fund schemes should one buy this year?”

    “Which is the best mutual fund scheme?”

    “Which is the best investment?”

    “Should I invest in stocks or real estate?”

    “What is your view of the stock market?”

    “Are my investments proper? Or should I make some changes?”

    We often overlook the investor needs while trying to answer such questions. Before trying to choose the right mutual funds, or any other instrument for your investment, you need to understand the investors’ needs first.

    • Financial Goals: Investments are linked to financial goals like children’s education, retirement, or buying a house.
      • For example, Shalini’s parents want to support her dream of becoming a space scientist, which requires financial planning for her education.  
    • Goal Setting: Prioritize goals based on importance and timeline (short-term vs. long-term).
      • Rabindra, an engineer, is planning for his retirement, a long-term goal. Surinder Singh wants to buy a house in the near future, a short-term goal.  

    Seven Habits of Highly effective people (by Stephen R Covey)

    UrgentNot Urgent
    Important
    Not Important

    Important but not-so-urgent tasks are not planned for in time until they become urgent.

    • Inflation: Account for inflation, which erodes purchasing power over time.
      • For instance, if Shalini’s higher education costs Rs. 50 lakhs today, it will cost significantly more in 10 years due to inflation.  (₹ 1,07,94,625 after 10 years)
      • While a future expense will depend on a lot of factors like course/university selected, but it is important to keep a baseline expense adjusted for inflation
    • Savings vs. Investments: Saving is setting aside money, while investing aims to grow it.
      • Saving is considered akin to ensuring the safety of money, 
      • Investment is done primarily with the objective of earning profit.  
    • Investment Factors: Evaluate investments based on:
      • Safety (risks involved),
      • liquidity (ease of converting to cash), 
      • returns (income or capital gains), 
      • Convenience (ease of investment, ease to take out money, check value of investments),
      • ticket size (minimum investment),
      • Taxability (lower tax, more tax before maturity),
      • Tax deductions (e.g. ELSS)
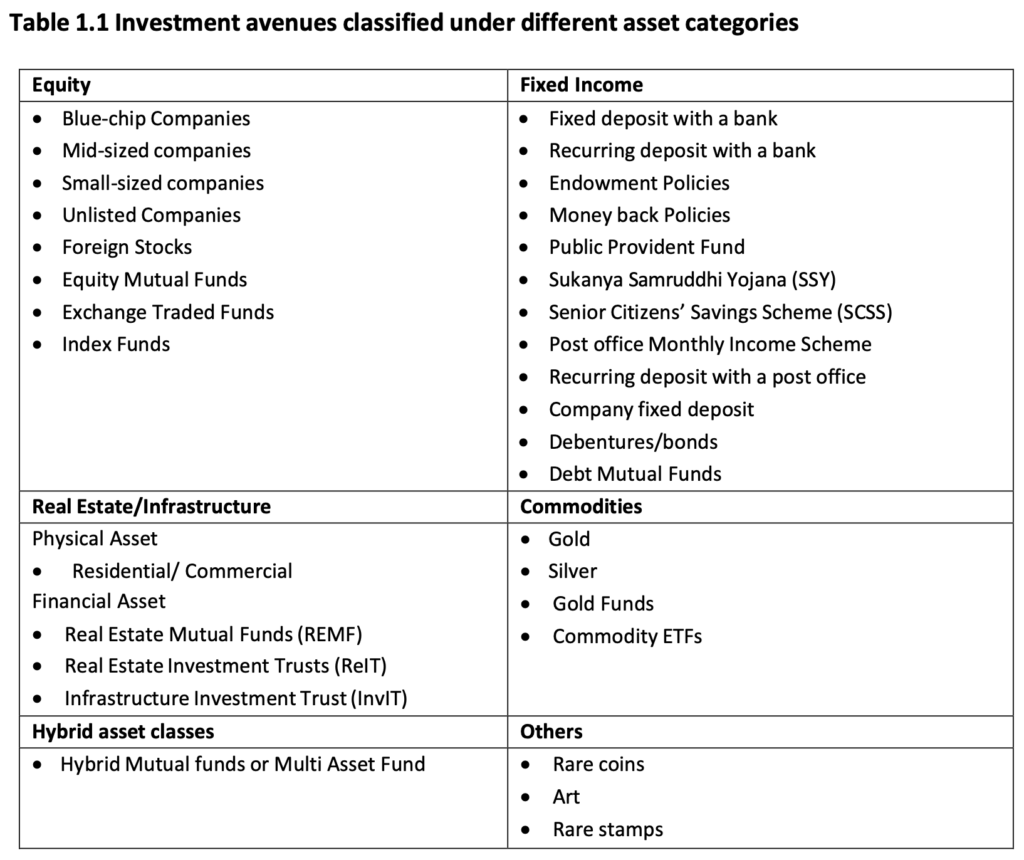
    • Asset Classes: Major asset classes include real estate, commodities, fixed income, and equity.
      • Real Estate:
        • In majority of cases, individuals purchase real estate for self-occupation
        • Can be for self-occupation or investment, but location is critical, and it’s relatively illiquid.  
      • Commodities:
        • Commodity contracts – largely short term contracts, allows large exposure with small money
        • Includes gold and silver, which can be used as investment avenues.  
      • Fixed Income:
        • Includes bonds and debentures, which can provide regular income.  
        • If person holds bonds till maturity, in almost all cases, there would be no capital gains
        • A transaction on bonds in secondary market – capital gains or losses
      • Equity:
        • Represents ownership in a business and carries risks and potential for higher returns.  
        • Equity share prices fluctuate a lot. However, over long periods of time, the share price follows the growth of the company. Historically, equity investing has generated returns in excess of inflation
        • Equity share owners also receive dividends from the company
    • Investment Risks: Mainly includes – Inflation risk, Liquidity risk, Credit risk, Market risk and Price risk
      • Inflation Risk:
        • For example, if inflation is 8% p.a., Rs. 10,000 today will be worth only Rs. 6,800 in purchasing power after 5 years. 
      •  Liquidity Risk:
        • Government securities offer safest investment, but to realise them without capital gains, need to hold them till maturity
        • Low liquidity in real estate, pre-mature withdrawal penalty in FDs 
      • Credit Risk:
        • Issue of bond does not pay or pay with delay
      • Market Risk and Price Risk:
        • Market Risk: When the price of all securities in a market falls due to a macro event like war, etc.
        • Industry specific risk/First specific risk
      • Interest Rate Risk:
        • Interest rate Increases, Bond prices fall
        • Drop in interest rate, increases value of investment
        • Longer maturity Instruments = More fluctuations
    Risk ManagementDiversification and asset allocation are key strategies for managing risk.
    – Avoid: Avoid certain instruments based on your risk profile.
    – Speculate: Take a position based on a certain expected event in the market, like falling interest rates.
    – Diversify: Diversification involves spreading investments across different asset classes to reduce risk.
    Behavioral BiasesBe aware of biases like overconfidence, herd mentality, and loss aversion, which can negatively impact investment decisions.

    For example, investors may miss out on critical information due to reliance on immediate examples or experiences.
    Asset AllocationDiversify investments across different asset classes to balance risk and return.

    Strategic asset allocation aligns with an individual’s financial goals, considering factors like return requirements, time horizon, and risk profile.

  • How to select the Right Mutual Fund

    How to select the Right Mutual Fund

    Navigating the world of mutual funds can be overwhelming with the numerous options available in the market. As an investor, understanding how to select the right schemes based on your investment goals is crucial for building a successful portfolio. In this guide, we’ll explore the key factors to consider when choosing mutual fund schemes.

    Understanding Investment Strategies

    The foundation of any mutual fund selection process begins with understanding different investment strategies and how they align with your financial goals.

    Active vs. Passive Funds

    • Passive funds (index funds, ETFs) aim to mirror benchmark indices with lower expense ratios
    • Active funds seek to outperform benchmarks through strategic stock selection
    • The trade-off: Active funds offer potential for higher returns but come with higher costs and the risk of underperformance

    Open-Ended vs. Close-Ended Funds

    • Open-ended funds provide liquidity with redemption at NAV but face the risk of fluctuating assets
    • Close-ended funds may offer higher return potential but have limited exit options before maturity
    • Consider your liquidity needs when choosing between these structures

    Diversification Spectrum

    Different funds offer varying levels of diversification:

    • Diversified funds (Multi-cap, Large-cap, Mid-cap) spread investments across sectors
    • Focused funds concentrate on fewer stocks, increasing potential returns but also risk
    • Sector funds invest in a single sector, carrying higher concentration risk
    • Thematic funds invest across sectors but follow a specific theme, offering moderate concentration

    Market Capitalization Strategy

    • Large-cap funds invest in established companies with stable revenues and lower risk
    • Mid-cap and small-cap funds target growing companies with higher risk-reward potential
    • Multi-cap and flexi-cap funds provide exposure across market segments

    Growth vs. Value Approach

    • Growth funds target companies expected to grow faster than average (higher risk)
    • Value funds seek undervalued stocks with price appreciation potential

    Specialized Fund Categories

    Debt Fund Options

    • Fixed Maturity Plans (FMPs): Close-ended debt funds with fixed maturity periods
    • Target Maturity Funds (TMFs): Open-ended alternatives to FMPs with high-quality securities
    • Short Duration Funds: Lower volatility options for 1-3 year horizons
    • Liquid and Ultra-Short Term Funds: Lowest risk options for very short-term parking of funds
    • Floater Funds: Options with steady NAVs despite interest rate fluctuations

    Hybrid and Alternative Options

    • Hybrid Schemes: Combination of debt and equity exposures for balanced portfolios
    • Dynamic Asset Allocation: Adjusts allocations based on market conditions
    • Gold Funds: Include ETFs tracking gold prices or funds investing in gold mining companies

    Evaluating Fund Performance and Management

    When comparing mutual fund schemes from different AMCs, consider:

    Fund Manager Expertise

    The fund manager’s experience and track record in identifying market trends can significantly impact performance.

    Performance Metrics

    • Compare returns relative to the benchmark over extended periods
    • Look for consistent outperformance in both bull and bear markets
    • Use cumulative returns data to evaluate different holding periods
    • For equity funds, focus on longer performance periods

    Portfolio Analysis

    • For equity funds: Check diversification, market segment exposure, cash holdings, and turnover
    • For debt funds: Evaluate portfolio maturity, credit risk profile, and interest vs. capital gains contribution

    Operational Factors

    • Fund age: Longer history provides better evaluation data
    • Fund size: Consider in context of investment universe (large for large-cap, smaller for mid/small-cap)
    • Portfolio turnover: High turnover may indicate higher costs and unsteady management
    • Expense ratio: Especially important for debt schemes and index funds

    Making the Final Selection

    Research Resources

    • Understand rating agency methodologies when reviewing their rankings
    • Remember that historical performance doesn’t guarantee future results
    • Consider the impact of taxes and exit loads on actual returns

    Choosing Scheme Options

    • Growth option: Allows compounding within the fund without annual taxation
    • Dividend payout: Provides regular income but depends on distributable surplus
    • Dividend reinvestment: Automatically reinvests distributions
    • Consider systematic withdrawal plans (SWPs) as an alternative to dividend payouts for regular income needs

    Conclusion

    Selecting the right mutual fund scheme requires careful consideration of your investment goals, risk tolerance, and time horizon. By understanding the different fund categories, evaluating performance metrics, and aligning investment strategies with your financial objectives, you can build a portfolio that works effectively toward your long-term financial success.

    Remember that diversification across fund types, regular monitoring, and periodic rebalancing are essential practices for maximizing your mutual fund investments over time.

  • Categorisation of Mutual Funds

    Categorisation of Mutual Funds

    SEBI Circular on Categorisation and Rationalisation of Mutual fund schemes, 2017

    SEBI has categorized all Mutual funds in 5 Broad categories:

    • Equity Schemes (11 sub-categories)
    • Debt Schemes (16 sub-categories)
    • Hybrid Schemes (6 sub-categories)
    • Solution Oriented Schemes (2 sub-categories)
    • Other Schemes (2 sub-categories)

    Equity Schemes (11 schemes)

    Multi Cap FundsMin 25% in Large Cap companies (1 – 100th company)Min 25% in Mid Cap companies (101st – 250th company)Min 25% in Small Cap companies (251st company onwards)
    Large Cap FundsMin 80% in Large cap companies
    Large & Mid CapMin 35% in Large + Min 35% in Mid
    Mid Cap FundsMin 65% in Mid Cap
    Small Cap FundsMin 65% in Small Cap
    Dividend Yield FundsMin 65% in equity + Majority in dividend yielding stocks
    Value Stocks or Contra FundMin 65% in equity stocksValue fund = Value Investment StrategyContra fund = Contrarian Investment Strategy
    Focussed FundMaximum 30 Stocks + Min 65% in equity
    Sectoral/ThematicMin 80% in equity of a particular sector
    ELSSStatutory lock-in of 3 years and tax benefitsMin 80% investment in equity
    Flexi-CapMin 65% investment in equityVaried investment across large, mid and small cap stocks

    Debt Schemes (16 schemes)

    All of the below debt schemes are Open-ended

    Overnight FundOvernight securities having maturity of 1 day 
    Liquid FundDebt and money market securities having maturity of 91 days (T-bills, bank bonds, etc.)
    Ultra short duration FundDebt and money market securities with Macaulay duration of portfolio between 3 to 6 months 

    Macaulay formula = Wtd avg time to receive a bond’s cash flows
    C = Coupon rate
    M = Maturity value

    Macaular Duration formula
    Low duration FundDebt and money market securities with Macaulay duration of portfolio between 6 months to 1 year 
    Money Market FundMoney market instruments with maturity up to 1 year
    Short Duration FundDebt and money market securities with Macaulay duration of portfolio between 1 to 3 years 
    Medium Duration FundDebt and money market securities with Macaulay duration of portfolio between 3 to 4 years
    Medium to Long Duration fundDebt and money market securities with Macaulay duration of portfolio between 4 to 7 years
    Long Duration fundDebt and money market securities with Macaulay duration of portfolio more than 7 years
    Dynamic bondInvesting across durations
    Corporate Bond FundMin 80% investment in AA+ and above rated corporate bonds
    Credit Risk FundMin 65% investment in AA and below rated corporate bonds
    Banking & PSU FundMin 80% investment in Bank and PSU debt instruments
    Gilt FundMin 80% investment in G Secs across maturity
    Gilt Fund with 10 yrMin 80% investment in G Secs so that Macaulay duration of portfolio is 10 years
    Floater FundMin 65% investment in floating rate instruments

    Hybrid Schemes (6 schemes)

    Conservative Hybrid Fund75-90% in debt instruments10-25% in equity and equity instruments
    Balanced Hybrid Fund40-60% in equity and equity related instruments40-60% in debt instrumentsNo arbitrage permitted
    Aggressive Hybrid Fund65-80% in equity and equity related instruments20-35% in debt instrumentsNote: Mutual funds in India can offer either Aggressive Hybrid Fund OR Balanced Fund
    Dynamic Asset Allocation/ Balanced AdvantageInvestment in equity/debt managed dynamically
    Multi Asset AllocationInvests in at least 3 asset classesMinimum 10% allocation in each asset classForeign securities not treated as separate asset class
    Arbitrage FundMinimum 65% in equityInvests in arbitrage opportunities
    Equity SavingsMinimum 65% in equityMinimum 10% in debtInvests in equity, arbitrage and debt

    Solution-Oriented Schemes (2 schemes)

    Retirement FundLock-in of 5 years or till retirement (whichever is earlier)For long-term retirement corpus planning
    Children’s FundLock-in of 5 years or till child’s majority (earlier of two)For building corpus for child’s future needs

    Other Schemes (9 schemes)

    Index Funds/ETFsMinimum 95% in securities of a specific index being tracked
    Fund of Funds (Overseas/ Domestic)Minimum 95% in underlying fund
    Fixed Maturity PlansClose-ended debt fundsPortfolio duration aligned with scheme maturity
    Target Maturity Date Funds (TMF)Debt funds with specific maturity dates (2-10 years)Invest in bonds with matching maturities
    Capital Protection Oriented FundsClosed-end hybrid fundsPart investment in debt instruments for capital protectionRemaining in equity derivatives for higher returns
    Infrastructure Debt FundsMinimum 90% in debt securities of infrastructure companies/projectsCan be set up as Trust (regulated by SEBI) or Company (regulated by RBI)
    Real Estate Mutual FundMinimum 75% in real estate assets, mortgage-backed securities, equity sharesAt least 35% in physical assetsClosed-end and listed on stock exchange
    ESG FundsSub-category under thematic equity schemesVarious strategies: Exclusion, Integration, Best-in-class, Impact investing, etc.
    Specialized Investment Fund (SIF)Minimum investment amount: Rs. 10 lakhs